Payment processing · Detroit, Michigan
B2B payment processing in Detroit, Michigan
Customers in Detroit still take terms. When they pay a large invoice by card, the fee on the statement is often higher than the rate you were sold. Their price stays the same. Card funds typically arrive in 1–2 business days. A free statement review takes three business days, and if there is no saving, we will say so.
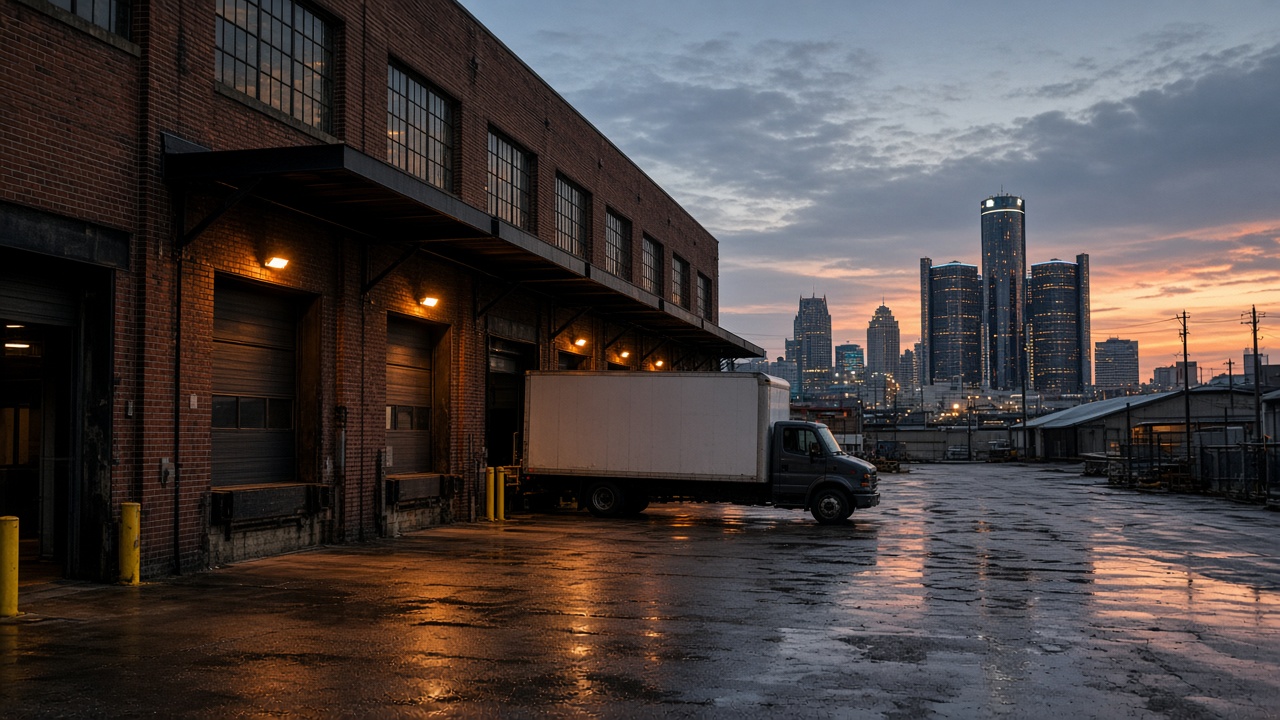
Detroit and Wayne County
Card fees on invoices that have already gone out the door.
Detroit distributors move automotive parts, steel, and industrial supplies across Wayne, Oakland, and Macomb counties, and over the Ambassador Bridge into Windsor. Buyers often hold 30–60 day terms, then pay a large invoice with a commercial card. The processing statement is where the rate you were quoted and the rate you paid come apart.
- Detroit
- Dearborn
- Warren
- Livonia
- Romulus
- Taylor
- Sterling Heights
- Pontiac
- Southfield
- Auburn Hills
The file is sized on the statement. A distributor in Detroit uses the same processing as any other approved account. Distributors on the Canadian side of the bridge can start with B2B payment processing in Windsor, Ontario. The full product is payment processing.
What a Detroit distributor is usually looking at
- A quoted rate that does not match the statement
- Commercial cards settling at a higher level
- Customers on 30–60 day terms
- Large invoices where a surcharge would push them off the card
Commercial cards
How a Detroit distributor's commercial card payment is priced.
Parts and industrial suppliers in Dearborn, Warren, and Livonia ship on the plant's schedule. The buyer often holds 30–60 days, then pays a released order with a purchasing card. The invoice looks collected. The fee is on the statement, and it depends on whether the invoice details were sent with the payment.
Business cards qualify for a lower rate when invoice details are sent with the payment. Industry estimates put the share of B2B card volume that misses that commercial rate at 40–60%. That is a range, not your file. The sources for that range are on the sources page, and the statement review measures the actual share.
The offer
Lower the fee. Leave their price alone.
Customers keep paying as they do today. You keep more of each card sale, and card funds typically arrive in 1–2 business days. If a review of the statement shows no saving, we will say so.
Customer price unchanged
We do not add a surcharge to the invoice. Their price stays the same, and they keep the card benefits they already use.
Funds in 1–2 business days
Card funds typically arrive in 1–2 business days, rather than waiting out 30–60 day terms. That window is a processing target, not a guarantee.
A free statement review
Three business days. No obligation. You get a written finding against your actual statement, whether or not there is a saving.
It posts to the invoice
Payment links, a customer portal, and reminders. The payment still posts in QuickBooks, Sage, Acumatica, and the other systems you already run.
Surcharge rules in the United States depend on the card network and the state. Confirm with counsel on a named file. On an $8,000–$47,000 invoice, a surcharge is a reason for the customer to leave the card. We treat it as the wrong default on large tickets. The full comparison sits on payment processing.
Who it fits
Distributors, controllers, and counter sales.
Built for wholesale and distribution businesses around $2M–$25M in sales, with commercial card volume. A statement is enough to start.
Wholesale distributors
Parts and industrial supplies go out on terms along I-94 and I-75. When the buyer pays the open invoice by card, the fee comes out of a margin that was already thin.
Controllers
The statement is the file. A free review in three business days shows what you pay today, and whether a lower fee is actually there.
Counter and inside sales
The customer is at the counter with a purchasing card. They should pay the same price. You should not give up the sale to keep the fee down.
Compared with waiting
Their due date, or a card payment this week.
Numbers below are the published targets. Your statement sets the figure. Nothing on this page is a quote.
| Waiting on terms | Novaline payment processing | |
|---|---|---|
| When cash arrives | On their terms, often 30–60 days | Typically 1–2 business days on card payments |
| Their price | Unchanged | Unchanged. No surcharge added by default |
| What you pay to accept the card | Whatever the statement says today | Reviewed against that statement |
| If there is no saving | The rate stays as it is | We say so |
| Where it posts | However you record the payment | To the invoice, in the system you already run |
On Detroit accounts
Where the card fee shows up.
A Dearborn parts house and a purchasing card
An $8,000 invoice paid by commercial card looks like a fast collection. The statement shows what that speed cost. The review puts a number on it.
Plant releases that bunch up
Card volume stacks for a few weeks, then the lane goes quiet. The rate on those busy weeks is the one worth reading, because that is where the fee adds up.
A rate that lived on a proposal
The number in the sales conversation and the number on the statement are often different. The audit uses the statement.
Questions
Payment processing, in plain language.
What is B2B payment processing for distributors in Detroit, Michigan?
It is card acceptance for wholesale and distribution businesses in Detroit and Wayne County. Customers keep the same price. You pay less to accept the card when the statement supports it, and card funds typically arrive in 1–2 business days.
Is B2B payment processing in Detroit a retail card terminal?
No. It is for distributor invoices paid with commercial or purchasing cards. A consumer store with no commercial card volume is outside this offer.
Does Novaline need an office in Detroit?
No. The file is the processing statement. Companies in Detroit, Dearborn, Warren, Livonia, Romulus, Taylor, Sterling Heights, Pontiac, Southfield, and Auburn Hills use the same review as any other distributor.
Why is a Detroit commercial card rate higher than the rate on the proposal?
Business cards qualify for a lower rate when invoice details are sent with the payment. When those details are missing, the transaction often misses the commercial rate. Industry estimates put that share at 40–60%. The statement review measures your actual share.
How fast do Detroit distributors get card funds?
Card funds typically arrive in 1–2 business days, versus 30–60 day terms on many distributor invoices. That window is a processing target, not a guarantee.
Will my Detroit customers pay a different price?
No. Their price stays the same. We do not add a surcharge to the invoice. They keep the card benefits they already use.
What does the fee audit include for a Detroit file?
Free, three business days, no obligation. You get a written finding against your actual statement, whether or not there is a saving. The calculator on the main payments page is an estimate. The audit is the verification.
Should a Detroit distributor surcharge large invoices?
Surcharge rules in the United States depend on the card network and the state. Confirm with counsel on a named file. On an $8,000–$47,000 invoice, a surcharge is a reason for the customer to stop paying by card. We treat it as the wrong default.
Who in metro Detroit is this for?
Wholesale and distribution businesses around $2M–$25M in sales, with commercial or purchasing-card volume. That includes companies in Detroit, Dearborn, Warren, Livonia, Romulus, Taylor, Sterling Heights, Pontiac, Southfield, and Auburn Hills. Consumer-only retailers are outside this offer.
Which accounting systems does this connect to?
Payments connect inside 100+ business systems, including QuickBooks, Sage, Acumatica, SAP, NetSuite, Microsoft Dynamics, Magento, BigCommerce, and Salesforce. The payment still posts to the invoice.
What should a Detroit distributor send to start?
One recent processing statement. We reply with a written finding within three business days and tell you whether a lower fee is there.